

The European construction and interior design market is undergoing a significant transformation driven by the convergence of regulatory pressure, sustainability commitments, and evolving design preferences.
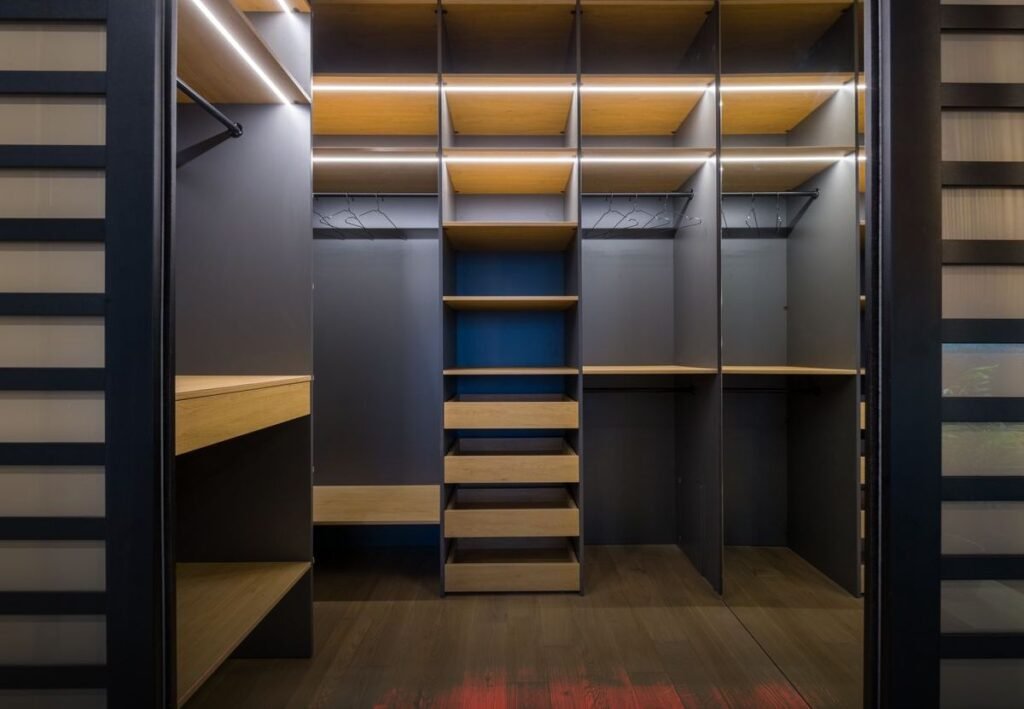
Among the surface materials that are seeing growing specification across European commercial construction, retail fit-out, healthcare facilities, and hospitality interiors is high pressure laminate – a product category whose technical performance, regulatory compliance profile, and sustainability credentials are becoming more important to European specifiers, architects, and procurement professionals with each passing year.
Understanding what high pressure laminate actually is, how it is manufactured, what regulatory standards govern its use in European building applications, and how the raw material supply chains that produce it are structured is increasingly relevant knowledge for European businesses operating in the construction, interior design, facilities management, and building materials distribution sectors.
What High Pressure Laminate Is and Why European Specifiers Choose It
High pressure laminate is a composite panel material produced by bonding multiple layers of resin-impregnated kraft paper with a decorative surface layer under high heat and pressure – typically exceeding 70 bar and 130 degrees Celsius during the pressing process. The resulting panel is a dense, rigid material with exceptional surface hardness, abrasion resistance, chemical resistance, and dimensional stability that makes it suitable for demanding interior surface applications where conventional painted or veneered surfaces would deteriorate rapidly under use.
In European commercial interior applications, HPL panels are widely specified for wall cladding in high-traffic public spaces including hospitals, schools, transport terminals, and retail environments where hygiene, durability, and cleanability are primary performance requirements. Furniture surfaces, laboratory worktops, locker systems, toilet partition systems, and kitchen surfaces in commercial catering environments all represent established HPL application categories across European markets.
The European market for HPL and compact laminate – a thicker, self-supporting variant of the same material – is one of the largest in the world, served by a combination of major European manufacturers and international producers whose products are distributed through specialist building materials channels throughout the EU single market.
EU Regulatory Requirements for HPL in Building Applications
The regulatory framework governing the specification of HPL in European building applications is multi-layered, reflecting the EU’s comprehensive approach to construction product safety and performance.
The Construction Products Regulation (EU) No 305/2011 provides the overarching framework for CE marking of construction products sold in the EU single market. For HPL panels used as wall and ceiling cladding in building applications, the relevant harmonized standard EN 438 – High Pressure Decorative Laminates – specifies the performance characteristics and test methods that define product properties including surface hardness, wear resistance, dimensional stability under humidity cycling, and reaction to fire.
Reaction to fire performance is a particularly significant regulatory consideration for HPL specified in European building applications. The Construction Products Regulation’s Euroclass system classifies construction products including surface materials into reaction to fire classes (A1, A2, B, C, D, E, F) based on standardized EN test methods. For HPL specified in applications where fire regulatory requirements apply – hospital corridors, public transport facilities, high-rise residential buildings, and other regulated building types – ensuring that the specified product carries appropriate Euroclass classification documentation is a compliance necessity that procurement teams cannot overlook.
REACH compliance, discussed extensively in the context of chemical products, also applies to HPL and the chemical inputs used in its manufacture. The resins, paper fiber materials, and decorative surface treatments used in HPL production involve chemical substances that must be appropriately registered and managed under REACH. For European building materials distributors and specifiers sourcing HPL from non-EU manufacturers, ensuring that the product’s chemical composition is REACH-compliant is a due diligence requirement that the EU supply chain obligations under REACH Article 33 make genuinely important.
The Raw Material Supply Chain: Polyester Staple Fiber’s Role in HPL Manufacturing
What most architects, interior designers, and building products procurement professionals do not know about HPL is that its manufacturing process may incorporate synthetic fiber materials alongside the kraft paper and resin layers that are more commonly associated with laminate construction. The role of polyester staple fiber in laminate manufacturing is a dimension of HPL material science that is rarely discussed in product specification literature but that has meaningful implications for the performance characteristics of the finished panel.
Polyester staple fiber incorporated into the core layers of HPL panels contributes to dimensional stability, impact resistance, and the mechanical properties that determine how the finished panel performs under the flexural and impact loads of real installation and service conditions. The fiber’s integration into the paper and resin matrix creates a composite structure with enhanced toughness compared to all-paper constructions, which is particularly relevant for compact laminate and exterior-grade HPL applications where mechanical performance requirements are more demanding.
For European building materials buyers and distributors sourcing HPL from Asian manufacturers – as a significant proportion of the European market does, given the manufacturing scale advantages of Asian HPL producers – understanding the fiber raw material inputs that go into HPL production is part of evaluating the material quality and consistency that specification-grade products require.
Polyester staple fiber for HPL applications is sourced predominantly from Chinese fiber manufacturers and exporters who have developed the product quality and export logistics capability to serve demanding international manufacturing customers. Yaakan Chemical Fiber, based in Xiamen with extensive experience supplying polyester fiber products to industrial buyers across more than fifty countries, supplies polyester staple fiber alongside their yarn product range to manufacturing buyers whose applications span textiles, nonwovens, and industrial composite materials including construction product applications.
Sustainability Credentials and the European Green Deal
The European Green Deal and its implementing legislation – including the EU Taxonomy for Sustainable Activities, the Ecodesign for Sustainable Products Regulation, and the forthcoming Digital Product Passport requirements – are creating new sustainability disclosure and performance obligations for construction products including surface materials like HPL.
For HPL manufacturers and distributors serving European markets, demonstrating environmental performance across the product lifecycle – from raw material sourcing through manufacturing, use phase, and end-of-life management – is becoming an increasingly important commercial requirement as European specifiers and building owners seek to meet their own sustainability commitments.
The fiber raw material inputs to HPL manufacturing have their own environmental footprint implications. Polyester staple fiber, derived from petrochemical feedstocks, contributes to the carbon footprint of HPL production in ways that European sustainability disclosure frameworks will increasingly require to be quantified and reported. The growing availability of recycled polyester fiber – produced from post-consumer PET waste rather than virgin petrochemical feedstocks – is creating supply chain options for HPL manufacturers seeking to reduce the embodied carbon of their products and substantiate recycled content claims that European specifiers increasingly value.
For European building materials buyers who are developing procurement policies aligned with their organizations’ sustainability commitments and with the requirements of green building certification systems including BREEAM and LEED, understanding the fiber supply chain behind HPL products – and the sustainability credentials of that supply chain – is part of making fully informed specification decisions.
Market Outlook for HPL in European Construction
The European HPL market is expected to see continued growth driven by several converging trends. The renovation wave that EU policy is promoting to improve the energy performance of the existing building stock creates significant demand for interior surface replacement that HPL is well positioned to serve. The healthcare sector’s ongoing investment in facility modernization – driven by infection control requirements that favor smooth, chemical-resistant, easily cleaned surfaces – is a sustained driver of HPL specification. And the retail and hospitality sectors’ ongoing need for durable, design-flexible surface materials that can withstand heavy use while maintaining attractive appearance continues to support HPL demand across commercial interior applications.
For European businesses in the construction materials distribution, interior design, and facilities management sectors, understanding HPL’s regulatory compliance requirements, performance characteristics, and raw material supply chain is knowledge that supports better specification decisions and stronger supplier relationships in a product category whose importance to European commercial interiors continues to grow.