Close Menu
    Latest Category
    • Finance
    • Tech
    • EU Law
    • Energy
    • About
    • Contact
    EUbusiness.com | EU news, business and politicsEUbusiness.com | EU news, business and politics
    Login
    • EU News
    • Focus
    • Guides
    • Press
    • Jobs
    • Events
    • Directory
    EUbusiness.com | EU news, business and politicsEUbusiness.com | EU news, business and politics
    Home » Russia, British Virgin Islands added to EU tax haven blacklist

    Russia, British Virgin Islands added to EU tax haven blacklist

    npsnps15 February 2023 Finance
    — Filed under: EU News Headline1 Russia Tax
    Share
    Facebook Twitter LinkedIn Pinterest Email
    Russia, British Virgin Islands added to EU tax haven blacklist

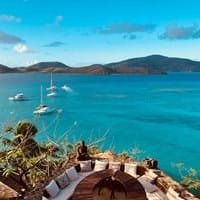
    Yachts in the sun – Photo by Nick Rickert on Unsplash

    (BRUSSELS) – The EU Council decided Tuesday to add Russia, the British Virgin Islands, as well as Costa Rica and Marshall Islands to the EU’s list of non-cooperative jurisdictions for tax purposes.

    Russia has been listed after the code of conduct group found it had not fulfilled its commitment to address the harmful aspects of a special regime for international holding companies (criterion 2.1). In addition, dialogue with Russia on matters related to taxation came to a standstill following the Russian aggression against Ukraine.

    Also North Macedonia, Barbados, Jamaica and Uruguay have been deemed to have successfully fulfilled their commitments and are removed from the state of play document.

    The EU list of non-cooperative tax jurisdictions now consists of 16 jurisdictions: American Samoa; Anguilla; Bahamas; British Virgin Islands; Costa Rica; Fiji; Guam; Marshall Islands; Palau; Panama; Russia; Samoa; Trinidad and Tobago; Turks and Caicos Islands; US Virgin Islands; Vanuatu.

    While the jurisdictions are now listed as non-cooperative on tax matters, they are invited to improve their legal framework in order to resolve the identified issues.

    This revised list (Annex I) includes countries that either have not engaged in a constructive dialogue with the EU on tax governance or have failed to deliver on their commitments to implement the necessary reforms. Those reforms should aim to comply with a set of objective tax good governance criteria, which include tax transparency, fair taxation and implementation of international standards designed to prevent tax base erosion and profit shifting.

    The code of conduct group, the EU Council body which prepares the updates of the list, is cooperating closely with international bodies such as the FHTP to promote tax good governance worldwide.

    For the Marshall Islands, there are concerns that this jurisdiction which has a zero or only nominal rate of corporate income tax is attracting profits without real economic activity (criterion 2.2 of the EU list). In particular, the Marshall Islands were found to be lacking in the enforcement of economic substance requirements. The Marshall Islands have been listed already once, in 2018. British Virgin Islands are listed because they were found not to be sufficiently in compliance with the OECD standard on exchange of information on request (criterion 1.2). This is the first time this jurisdiction is listed.

    For the first time since the list was established, Costa Rica is included because it has not fulfilled its commitment to abolish or amend the harmful aspects of its foreign source income exemption regime (criterion 2.1).

    Council conclusions on the revised EU list of non-cooperative jurisdictions for tax purposes

    EU list of non-cooperative jurisdictions (background information)

    Code of Conduct Group (Business Taxation)

    Add A Comment
    Leave A Reply Cancel Reply

    You must be logged in to post a comment.

    nps
    • Website

    Related Content

    European Central Bank governing council meeting - Photo © European Central Bank 2026

    ECB faces tough decision in October as equities begin to wilt under high interest rates

    Business finance Frankfurt - Image by Kai Pilger from Pixabay

    €10.9 trillion in value added to EU businesses in 2024

    E-commerce - Photo by Antoni Shkraba Studio on Pexels

    European e-commerce reaches €911 billion in 2025, as sector calls for fairer competition

    Sponsor: EuroCommerce22 September 2026
    IHI logo

    Accounting and Finance Correspondent, Innovative Health Initiative Joint Undertaking, IHI JU

    Business growth green invest scaleup - Image by Nattanan Kanchanaprat from Pixabay

    ECON committee backs smaller SFDR scope and opens transition category to fossil fuels

    Sponsor: WWF10 September 2026
    Von der Leyen - Nielsennister - Frederiksen - Photo Aurore Martignoni © European Union 2026

    EU and Greenland strengthen partnership with €200m EU investment

    LATEST EU NEWS
    Booking.com - Photo by Jas Rolyn on Unsplash

    EU launches probe into Booking.com scams and fraud

    21 October 2026
    Fishing boat

    Brussels charts new vision for EU fisheries and aquaculture sector

    20 October 2026
    Organic farming - Photo by Steven Weeks on Unsplash

    EU Council and Parliament strike deal to update rules on organic farming

    20 October 2026
    Arctic - Photo by stein egil liland on Pexels

    New EU strategy to strengthen security in the Arctic

    20 October 2026
    Airport terminal - Photo by Pim de Boer on Unsplash

    Final green light for better enforcement of passenger rights in the EU

    20 October 2026

    Subscribe to EUbusiness Week

    Get the latest EU news

    CONTACT INFO

    • EUbusiness, 117 High Street, Chesham Buckinghamshire, HP5 1DE, United Kingdom
    • +44(0)20 8058 8232
    • service@eubusiness.com

    INFORMATION

    • About Us
    • Advertising
    • Contact Info

    Services

    • Cookie Policy
    • Terms
    • Disclaimer

    SOCIAL MEDIA

    Facebook
    eubusiness.com © EUbusiness Ltd 2026

    Type above and press Enter to search. Press Esc to cancel.

    Manage Consent
    To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
    Functional Always active
    The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
    Preferences
    The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
    Statistics
    The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
    Marketing
    The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
    • Manage options
    • Manage services
    • Manage {vendor_count} vendors
    • Read more about these purposes
    View preferences
    • {title}
    • {title}
    • {title}

    Sign In or Register

    Welcome Back!

    Login to your account below.

    Lost password?